Stay updated with the latest company news, product innovations, exhibition highlights, and industry trends. Explore valuable insights into pressure vessel technologies and global markets.
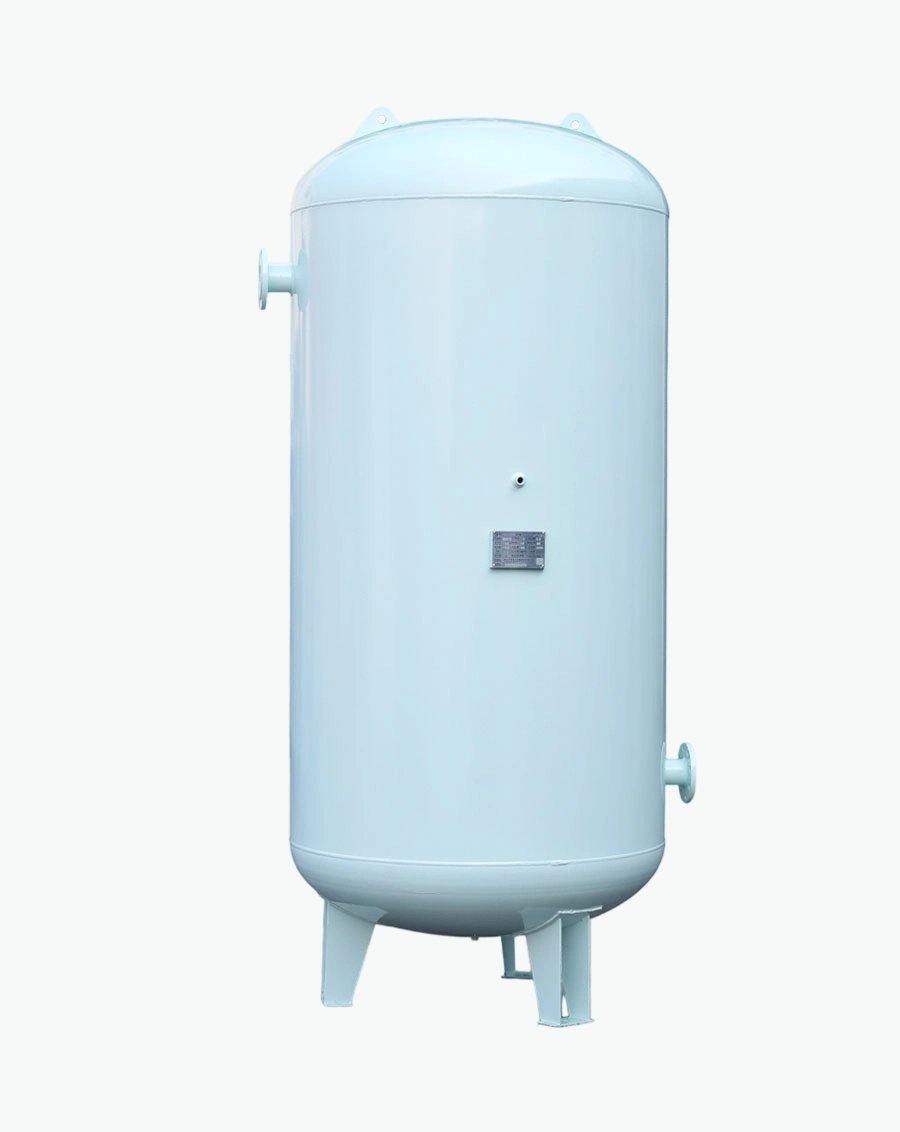
Emerging markets across Southeast Asia, the Middle East, and Africa represent high-growth opportunities for air receiver tank manufacturers though presenting distinct challenges requiring tailored strategies. These regions collectively account for approximately 15-18% of global compressed air equipment demand currently though projected to capture 25-30% share by 2035 driven by rapid industrialization, infrastructure development, and manufacturing relocation trends. Understanding nuanced demand patterns, regulatory environments, competitive dynamics, and customer preferences proves essential for successful market penetration and sustainable growth.
Unlike mature markets characterized by replacement demand and efficiency upgrades, emerging economies exhibit greenfield installation dominance creating different specification requirements, pricing sensitivities, and service expectations. Local manufacturing capabilities remain underdeveloped necessitating imports though trade policies increasingly favor domestic production through tariffs, local content requirements, and technology transfer mandates. Navigating these complexities demands deep regional knowledge, flexible business models, and long-term commitment beyond transactional export approaches.
This comprehensive analysis examines air receiver tank market characteristics across key emerging regions providing actionable insights for manufacturers seeking expansion. By understanding how Southeast Asian industrialization, Middle Eastern diversification initiatives, and African development trajectories shape compressed air infrastructure needs, organizations develop targeted strategies capturing growth while managing risks inherent in volatile emerging economies. Case studies illustrate successful market entry approaches highlighting best practices and common pitfalls.
Southeast Asia encompasses ten ASEAN nations plus Timor-Leste representing diverse economic development stages from highly advanced Singapore to emerging Laos and Myanmar. Combined
GDP of $3.6 trillion supports growing industrial base attracting foreign direct investment totaling $174 billion in 2023. Key growth drivers include:
Manufacturing Relocation: Supply chain diversification away from China accelerates as geopolitical tensions and rising labor costs prompt multinational corporations establishing alternative production bases. Vietnam emerged as primary beneficiary receiving $23 billion FDI in 2023 primarily targeting electronics assembly, textile manufacturing, and furniture production. Thailand attracts automotive investments ($8.5 billion) leveraging established supplier networks. Indonesia and Malaysia capture chemical processing and resource beneficiation projects.
Each manufacturing facility requires compressed air infrastructure creating receiver tank demand proportional to production scales. Electronics factories typically install 500-2000 m³/min compressor capacity needing 5,000-20,000 liters storage. Automotive plants require 2000-5000 m³/min with 20,000-50,000 liters storage. Textile mills operate 200-800 m³/min systems with 2,000-8,000 liters receivers. Cumulative effects across hundreds of new facilities generate substantial equipment volumes.
Infrastructure Development: Government infrastructure spending totals $150 billion annually across the region funding transportation networks, energy facilities, water treatment plants, and urban utilities. Construction activities utilize compressed air extensively for pneumatic tools, concrete spraying, and tunneling operations creating temporary though significant demand. Permanent installations in completed infrastructure (airport HVAC systems, subway ventilation, water plant instrumentation) provide ongoing receiver tank requirements.
Belt and Road Initiative projects contribute additional investments though facing increased scrutiny regarding debt sustainability. Japan, South Korea, and European countries compete offering alternative financing reducing Chinese dominance. Competition among funders benefits recipient countries through better terms though complicating procurement standardization.
Urbanization and Consumer Goods: Rising middle classes (projected 350 million people by 2030) drive consumer goods manufacturing expansion including food processing, beverage production, pharmaceuticals, and personal care products. These industries require hygienic compressed air systems meeting strict quality standards favoring stainless steel receivers despite cost premiums. Urban population growth (2.5% annually) stimulates construction boosting related compressed air applications.
Cold chain development supporting food distribution requires refrigerated warehouses utilizing compressed air for refrigeration controls and material handling. E-commerce expansion drives logistics center construction needing pneumatic sorting systems. Healthcare infrastructure improvements build hospitals requiring medical air systems with certified receivers.
Vietnam: Fastest-growing manufacturing hub with 7% annual GDP growth. Electronics sector dominates (Samsung, LG, Foxconn facilities) demanding high-quality compressed air for precision assembly. Government incentives include tax holidays, land subsidies, and streamlined approvals attracting investors. Local content requirements gradually increasing from 30% to 60% pressuring foreign suppliers establishing local partnerships.
Receiver tank specifications favor international standards (ASME, PED) though accepting Chinese GB certifications for cost-sensitive projects. Price sensitivity remains high with buyers comparing multiple quotes extensively. Payment terms often extend 90-120 days straining supplier cash flows. Quality consciousness improving though still secondary to cost for many purchasers.
Distribution channels rely heavily on local agents familiar with bureaucratic processes navigating customs clearance, tax registrations, and technical standards compliance. Direct sales prove challenging without local presence though representative offices establish relationships supporting agent networks. After-sales service expectations increase as facilities gain experience though maintenance capabilities remain limited requiring supplier support.
Thailand: Mature manufacturing base with strong automotive sector (Toyota, Honda, Ford plants) and growing electronics industry. Eastern Economic Corridor development attracts $50 billion investments in advanced manufacturing, digital industries, and innovation hubs. Skilled workforce and established supply chains provide advantages though labor costs exceed Vietnam and Indonesia.
Quality standards align closely with Japanese practices reflecting decades of Japanese investment. Stainless steel adoption higher than regional averages particularly in automotive and food processing sectors. Energy efficiency awareness grows driven by rising electricity costs and government conservation programs. Smart monitoring interest increases though budget constraints limit
immediate adoption.
Local manufacturing capabilities exist for standard carbon steel receivers though custom designs and specialty materials require imports. Import duties range 5-15% depending on product classification and origin country. ASEAN Free Trade Area preferences reduce tariffs for member state sources encouraging regional sourcing strategies. Technical support infrastructure relatively developed enabling faster service response.
Indonesia: Largest Southeast Asian economy ($1.4 trillion GDP) with abundant natural resources driving mining, palm oil processing, and petrochemical industries. Manufacturing contributes 20% of GDP though government targets 30% through downstream processing initiatives banning raw material exports forcing domestic value addition. Nickel processing for electric vehicle batteries
attracts $15 billion investments creating compressed air demand.
Geographic dispersion across 17,000 islands complicates logistics increasing delivery costs and lead times. Jakarta-based headquarters concentrate decision-making though actual installations spread throughout archipelago requiring extensive distribution networks. Infrastructure limitations (port congestion, road conditions, power reliability) affect project execution timelines necessitating
contingency planning.
Corruption perceptions remain elevated requiring careful compliance management. Local partner selection proves critical navigating regulatory complexity though introducing dependency risks.
Payment security concerns warrant letters of credit or advance payments protecting suppliers.
Currency volatility (rupiah fluctuations ±10% annually) creates pricing challenges requiring hedging strategies or frequent adjustments.
Malaysia: Developed economy with strong electronics manufacturing (penang semiconductor cluster), oil and gas services, and palm oil processing. Multicultural society facilitates international
business though Bumiputera policies reserve certain contracts for ethnic Malay companies requiring joint venture structures. English proficiency enables easier communication compared to neighbors. Quality expectations approach developed market levels with international certifications mandatory for most industrial applications. Environmental regulations tightening requiring compliant coating systems and waste disposal procedures. Energy efficiency standards align with international benchmarks pushing premium product adoption. Smart factory initiatives promote IIoT integration creating opportunities for monitored receivers.
Local fabrication capabilities serve standard requirements though specialized applications import from Singapore, Japan, or Europe. Free trade agreements with major economies reduce tariff barriers facilitating imports. Professional service sector supports complex projects with engineering consultants specifying equipment. Maintenance infrastructure well-developed enabling third-party service provision.
Market structure exhibits fragmentation with numerous players competing across segments:
International Brands: Atlas Copco, Ingersoll Rand, Kaeser maintain strong positions through established distribution networks and brand recognition. Premium pricing (20-40% above local alternatives) justified through perceived quality, reliability, and service support. Focus on large accounts and multinational customers willing to pay premiums for reduced risk.
Regional headquarters in Singapore coordinate Southeast Asian operations leveraging proximity and infrastructure. Local assembly operations in Thailand and Malaysia reduce costs while maintaining quality control. Technology transfer arrangements with local partners enable market access though risking intellectual property exposure.
Chinese Suppliers: Hangzhou Hangyang, Shanghai Compressor, and numerous smaller manufacturers compete aggressively on price offering 30-50% discounts versus international brands. Quality improved significantly though perception lags reality creating education challenges.
Government export subsidies enhance competitiveness though triggering anti-dumping investigations in some markets.
Direct sales teams bypass distributors improving margins though requiring substantial investments. Online platforms facilitate initial contacts though closing deals demands face-to-face relationship building. After-sales service gaps create vulnerabilities competitors exploit through superior support positioning.
Local Manufacturers: Each country hosts domestic producers serving price-sensitive segments with basic carbon steel receivers. Limited engineering capabilities restrict offerings to standard designs though adequate for many applications. Relationships with local customers provide advantages navigating bureaucracy and cultural nuances. Foreign competition threatens though protectionist policies shield incumbents.
Joint ventures with international partners upgrade capabilities through technology access while maintaining local ownership satisfying regulatory requirements. Success depends on partner compatibility balancing knowledge transfer against competitive threats. Exit strategies prove complex unwinding intertwined operations.
Successful market penetration requires multifaceted approaches:
Distribution Network Development: Identify qualified agents demonstrating technical competence, financial stability, and market access. Exclusive territories motivate investment though requiring performance commitments. Regular training updates product knowledge and selling techniques. Joint marketing activities build brand awareness sharing costs.
Performance metrics track sales volumes, pipeline development, customer satisfaction, and payment collection. Quarterly business reviews assess progress addressing issues proactively. Termination clauses protect interests though relationships prefer collaborative resolution. Backup distributors prevent single-point dependencies.
Local Presence Establishment: Representative offices demonstrate commitment facilitating customer interactions though not conducting transactions directly. Staff hiring balances expatriate expertise with local market knowledge. Visa and work permit processes require patience navigating bureaucratic requirements. Cultural adaptation proves essential building trust with local stakeholders.
Gradual progression from representatives to sales subsidiaries to manufacturing facilities scales commitment as market validation occurs. Each step requires additional investments though deepening market integration. Exit options remain available though becoming costlier with increased sunk investments.
Product Adaptation: Tropical climate specifications address high humidity (80-95% RH) and temperatures (30-35°C) accelerating corrosion. Enhanced coating systems, stainless steel options, and improved drainage designs accommodate harsh conditions. Voltage variations (220-240V, 50Hz) require electrical component compatibility though less relevant for passive receivers.
Packaging improvements protect against rough handling during multi-modal transport combining trucks, barges, and ships. Corrosion protection extends beyond standard VCI wrapping incorporating desiccants and robust cradling. Documentation translations into local languages (Thai, Vietnamese, Indonesian, Malay) facilitate customs clearance and user comprehension.
Pricing Strategies: Tiered pricing accommodates diverse customer segments with premium, standard, and economy offerings. Volume discounts incentivize larger orders though minimum thresholds prevent margin erosion. Payment term flexibility balances competitiveness against cash flow risks. Letters of credit provide security though adding complexity and costs.
Currency hedging protects against devaluation though proving difficult in illiquid forward markets.
Dollar-denominated contracts shift exchange risk to buyers potentially reducing competitiveness.
Local currency pricing requires active management adjusting for inflation and depreciation.
Transparent pricing builds trust though limiting negotiation flexibility valued in Asian business culture.
Middle Eastern economies undergo dramatic transformations diversifying beyond oil dependence creating compressed air infrastructure demand:
Saudi Vision 2030: Ambitious program targeting non-oil GDP contribution increase from 15% to 50% through massive investments in manufacturing, tourism, entertainment, and technology. NEOM megacity project allocates $500 billion developing futuristic urban center requiring extensive utility infrastructure including compressed air systems. Red Sea Project, Qiddiya entertainment city, and Diriyah Gate cultural district similarly drive construction activities.
Industrial cities expand manufacturing capacity in petrochemicals, pharmaceuticals, food processing, and building materials. Local content requirements mandate 40-70% domestic value creation pressuring foreign suppliers establishing local operations. Saudization policies require workforce nationalization creating talent acquisition challenges though developing local capabilities long-term.
Government procurement dominates initially though private sector participation grows through public-private partnerships. Payment reliability improves with sovereign backing though bureaucratic processes extend approval timelines. Relationship building proves essential navigating wasta (influence) networks though anti-corruption campaigns reduce overt graft improving transparency.
UAE Diversification: Dubai and Abu Dhabi pursue knowledge-based economies reducing oil reliance through tourism, logistics, financial services, and advanced manufacturing. Dubai Industrial Strategy 2030 targets manufacturing GDP contribution doubling to 25% focusing on aerospace, pharmaceuticals, food technology, and machinery. Free zones offer tax incentives, full foreign ownership, and streamlined regulations attracting multinational investments.
Expo 2020 legacy projects continue driving infrastructure development though at reduced pace post-event. World Cup 2034 preparations in neighboring Qatar stimulate regional construction
creating spillover opportunities. Renewable energy transitions (solar farms, green hydrogen) require compressed air for various processes though volumes remain modest relative to traditional industries.
High per-capita incomes support premium product acceptance though value consciousness increases amid economic diversification pressures. Quality expectations align with international standards requiring certified equipment. After-sales service differentiation proves critical as customers recognize lifecycle cost importance beyond initial prices.
Qatar National Vision 2030: Post-World Cup infrastructure utilization focuses on industrial development leveraging LNG revenues. North Field Expansion project increases gas production
requiring extensive compression infrastructure. Manufacturing zones develop downstream petrochemical processing creating receiver tank demand. Education and healthcare expansions build facilities needing specialized compressed air systems.
Small market size ($200 billion GDP) limits absolute volumes though high spending per capita supports premium positioning. Relationship-driven business culture requires long-term engagement before securing contracts. Sponsorship requirements mandate local partners though recent reforms relax restrictions for strategic sectors.
Oil and Gas Downstream: Refining and petrochemical complexes represent largest industrial compressed air consumers requiring rugged equipment suited to harsh desert environments. High ambient temperatures (45-50°C summer) challenge cooling systems necessitating oversized aftercoolers and enhanced ventilation. Sand ingress protection prevents abrasive damage to instruments and moving parts.
Corrosion from sour gas (H■S-containing) environments demands specialized materials including duplex stainless steels and nickel alloys. Internal coatings resist acidic condensate formed from sulfur compounds. Explosion-proof certifications mandatory for hazardous area installations. Safety standards exceed general industrial requirements reflecting catastrophic consequence potentials.
Maintenance accessibility proves critical given remote locations and extreme working conditions.
Modular designs enable component replacement without complete shutdowns minimizing production losses. Spare parts availability prevents extended downtimes waiting for imports. Local stockpiling strategies balance inventory costs against outage risks.
Construction and Infrastructure: Megaprojects consume massive compressed air volumes for pneumatic tools, shotcrete application, tunnel boring, and foundation drilling. Temporary installations prioritize rapid deployment and easy relocation over long-term durability. Rental markets thrive serving short-duration projects avoiding capital commitments.
Dust protection becomes paramount in desert construction sites preventing equipment failures from particulate infiltration. Portable receivers with integrated compressors simplify logistics though sacrificing efficiency compared to centralized systems. Noise restrictions near urban areas require soundproof enclosures adding costs.
Project financing structures influence procurement decisions with contractors preferring low upfront costs transferring expenses to clients through change orders. Performance bonds guarantee completion though tying up capital. Payment delays common requiring working capital buffers sustaining operations during receivable periods.
Food and Beverage Processing: Halal certification requirements dominate food industry specifications affecting compressed air system designs. Oil-free compression mandatory preventing contamination violating religious dietary laws. Stainless steel receivers with sanitary finishes meet hygiene standards though commanding premiums.
Hot climate challenges cold chain maintenance requiring reliable refrigeration dependent on compressed air controls. Backup systems prevent spoilage from power outages causing massive losses. Monitoring ensures continuous operation alerting staff to deviations before products compromise.
Export-oriented processors serving international markets adopt global standards (ISO 22000, HACCP) requiring documented compressed air quality verification. Receiver tanks contribute to compliance through appropriate materials and maintenance records. Audit readiness demands organized documentation accessible during inspections.
Healthcare Development: Hospital construction booms across Gulf states upgrading healthcare infrastructure to world-class standards. Medical air systems require NFPA 99 or equivalent compliance mandating oil-free compression, redundant receivers, and continuous monitoring.
Stainless steel 316L electropolished construction eliminates contamination risks.
Certification processes involve rigorous testing and documentation supporting accreditation (JCI, CBAHI). Qualified technicians perform maintenance ensuring ongoing compliance. Emergency backup power maintains critical systems during outages preventing patient safety compromises. Liability concerns motivate conservative specifications exceeding minimum requirements.
Government healthcare privatization introduces competition improving efficiency though maintaining quality standards. Private operators balance cost pressures against reputation risks selecting reliable equipment despite premiums. Long-term service contracts ensure continuity transferring operational responsibilities to specialists.
Navigating Middle Eastern regulatory landscapes requires attention to detail:
SASO Certification (Saudi Arabia): Saudi Standards, Metrology and Quality Organization mandates conformity assessment for pressure vessels entering kingdom. Approved certification bodies conduct evaluations verifying compliance with SASO standards referencing international codes (ASME, EN) with local amendments. Process takes 4-8 weeks costing $2,000-5,000 per model.
Labeling requirements include Arabic language warnings, manufacturer information, and certification marks. Packaging must display SASO logo preventing customs rejection. Pre-shipment inspections verify compliance though adding logistical complexity. Authorized representatives facilitate applications though requiring formal appointments registered with SASO.
ESMA Registration (UAE): Emirates Standardization and Metrology Department operates similar certification scheme though recognizing GCC (Gulf Cooperation Council) standards harmonizing requirements across member states. ECAS (Emirates Conformity Assessment Scheme) streamlines processes for approved manufacturers reducing duplication. Validity periods typically 3 years requiring renewal with updated documentation.
Dubai Municipality imposes additional requirements for construction equipment including noise limits and emission standards. Permit acquisitions authorize installations verifying structural adequacy and safety compliance. Inspections during and after installation confirm adherence to approved plans.
Violations trigger fines and work stoppages until corrected.
Civil Defense Approvals: Fire safety regulations govern pressure vessel installations requiring relief valve capacity calculations, discharge routing away from ignition sources, and emergency shutoff provisions. Civil Defense departments review plans issuing permits before commissioning. Annual inspections verify ongoing compliance though enforcement varies by emirate.
Hazmat classifications apply if receivers previously contained hazardous gases requiring cleaning certificates. Transportation regulations restrict pressurized vessel movements requiring special permits. Storage limitations prevent excessive inventories in populated areas reducing fire risks. Compliance demonstrates due diligence protecting against liability claims.
Market access strategies balance control against local knowledge:
Exclusive Distributors: Established trading houses possess relationships, market intelligence, and logistical capabilities accelerating market entry. Exclusivity motivates investment though requiring performance guarantees preventing complacency. Territory definitions prevent channel conflicts though gray market imports undermine arrangements requiring vigilance.
Compensation structures combine margins (15-25%), volume rebates, and marketing support aligning incentives. Training programs build technical competence enabling proper positioning against competitors. Joint customer visits strengthen relationships while educating distributors on value propositions. Regular communication maintains alignment addressing issues before escalation.
Exit provisions protect interests though termination disrupts customer relationships requiring transition planning. Non-compete clauses prevent distributors immediately representing competitors leveraging acquired knowledge. Intellectual property protections safeguard proprietary information though enforcement proves challenging across jurisdictions.
Joint Venture Structures: Local partners provide market access, regulatory navigation, and government relations though sharing profits and control. Ownership splits vary from 51/49 (local majority) to 50/50 balanced arrangements depending on sector restrictions. Management committees make strategic decisions requiring consensus potentially slowing responses.
Technology transfer obligations balance capability building against competitive risks. Phased approaches start with assembly progressing to design and eventually independent development. Milestone-based transfers link knowledge sharing to performance achievements ensuring mutual benefits. Legal frameworks govern disputes though preferring negotiated resolutions preserving relationships.
Cultural compatibility proves critical for partnership success beyond financial considerations. Shared values, communication styles, and long-term visions sustain collaborations through inevitable challenges. Due diligence investigates partner backgrounds verifying financial health, reputation, and strategic fit. Trial periods test compatibility before committing substantial resources.
Direct Operations: Establishing wholly-owned subsidiaries provides maximum control though requiring significant investments and local knowledge acquisition. Employment visa quotas mandate national hiring percentages creating talent challenges. Office setup navigates commercial licensing, municipal approvals, and utility connections consuming time and resources.
Gradual scaling tests market potential before committing fully. Representative offices conduct market research and relationship building without transaction authority. Sales subsidiaries add commercial capabilities though remaining dependent on imported products. Manufacturing facilities represent ultimate commitment requiring feasibility studies validating demand sufficient supporting local production.
Government incentives sometimes offset establishment costs through land grants, tax holidays, and subsidized utilities. Free zone locations offer additional benefits though restricting domestic market access requiring separate structures. Strategic location selections balance operational efficiency against market proximity and regulatory advantages.
Africa encompasses 54 countries with vastly different development levels creating heterogeneous market requiring segmented approaches. Combined GDP of $2.9 trillion supports growing though fragmented industrial base. Key characteristics include:
Infrastructure Deficits: Limited electricity access (43% of population), poor road networks, and inadequate port facilities constrain industrial development though creating opportunities for
improvement projects. Compressed air infrastructure supports construction activities building foundational infrastructure though volumes remain modest relative to other regions. Power reliability issues necessitate backup generators complicating compressed air system designs.
Urbanization rates (3.5% annually) drive city growth stimulating construction and consumer goods manufacturing. However, informal sectors dominate employment limiting formal industrial compressed air demand. Middle class expansion (projected 1.1 billion people by 2060) gradually increases purchasing power supporting manufactured goods consumption and related production facilities.
Resource Extraction Dominance: Mining operations (South Africa platinum, DRC cobalt, Zambia copper, Ghana gold) represent largest industrial compressed air users requiring heavy-duty equipment suited to remote locations. Harsh operating conditions including dust, temperature extremes, and limited maintenance access demand robust designs. Safety standards reflect hazardous environments though enforcement varies significantly.
Oil and gas production (Nigeria, Angola, Algeria, Libya) utilizes compressed air extensively though political instability affects investment consistency. Local content policies mandate domestic participation though capabilities lag requiring foreign partnerships. Currency shortages complicate payments necessitating creative financing structures.
Manufacturing Enclaves: Industrial clusters develop around ports (Durban, Lagos, Mombasa, Dar es Salaam) and capital cities benefiting from infrastructure concentration. Automotive assembly (South Africa, Morocco), food processing (Kenya, Ethiopia, Nigeria), and textiles (Ethiopia, Madagascar) create focused demand pockets. Special economic zones offer incentives attracting foreign investment though success varies widely.
Import dependence remains high with limited local manufacturing capabilities for industrial equipment. Logistics challenges increase costs and lead times requiring inventory buffering. Customs inefficiencies delay clearances adding uncertainty to project schedules. Regional trade agreements (AfCFTA) promise improvement though implementation progresses slowly.
South Africa: Most industrialized African economy ($400 billion GDP) with established manufacturing base in automotive (BMW, Mercedes, Toyota plants), mining equipment, and food processing. Skilled workforce and developed infrastructure provide advantages though load shedding (planned power outages) disrupts operations requiring backup solutions.
Receiver tank specifications follow international standards (ASME, SANS) with quality consciousness approaching developed market levels. Stainless steel adoption increases in food and pharmaceutical sectors. Energy crisis drives efficiency investments creating opportunities for optimized systems.
Maintenance infrastructure well-developed enabling third-party service provision.
Political uncertainty and policy unpredictability create investment hesitancy though fundamental economic strengths persist. Currency volatility (rand fluctuations) affects pricing requiring hedging or frequent adjustments. Labor relations prove contentious with strike risks disrupting production.
Security concerns necessitate protective measures for valuable equipment.
Nigeria: Largest African population (220 million) and economy ($500 billion GDP) though industrialization lags demographics. Oil revenues dominate government finances creating volatility from price fluctuations. Manufacturing contributes 10% of GDP with food processing, cement production, and beverages leading sectors. Infrastructure deficits constrain growth though gradual improvements occur.
Import restrictions and foreign exchange shortages complicate equipment procurement requiring creative structuring. Local assembly operations circumvent some barriers though facing component import challenges. Corruption perceptions remain elevated requiring careful compliance management. Security issues in certain regions limit market access though southern commercial centers remain relatively stable.
Price sensitivity dominates purchasing decisions with Chinese suppliers gaining share through aggressive pricing. Quality awareness improves among multinational facilities though local companies prioritize affordability. Payment security concerns warrant advance payments or letters of credit. Relationship building proves essential navigating bureaucratic complexities.
Kenya: East African hub with stable governance and growing manufacturing sector (food processing, pharmaceuticals, textiles). Mombasa port serves landlocked neighbors (Uganda, Rwanda, Burundi, DRC) creating distribution advantages. Special economic zones attract foreign investment through tax incentives and streamlined procedures. English proficiency facilitates business communications. Receiver tank demand grows with industrial expansion though from small base. Quality expectations moderate with international certifications preferred but not always mandatory. Energy costs remain high driving efficiency interest. Mobile money penetration enables innovative payment solutions though B2B transactions still rely on traditional banking.
Regional integration through East African Community expands addressable market though non-tariff barriers persist. Cross-border logistics prove challenging requiring experienced freight forwarders. Political stability supports long-term planning unlike some neighbors. Climate variations (highland cool vs coastal heat) affect specification requirements.
Egypt: Large population (110 million) and strategic location bridging Africa and Middle East create unique positioning. Government infrastructure investments (new capital city, road networks, energy projects) stimulate construction compressed air demand. Manufacturing zones develop textile, automotive, and electronics industries though facing foreign exchange constraints.
Import licensing and customs procedures prove cumbersome requiring local partner assistance. Currency devaluations affect pricing competitiveness though export opportunities emerge from weaker pound. Energy subsidies reduction increases efficiency awareness creating upgrade opportunities. Political transitions create uncertainty though military-backed government provides stability.
Mediterranean and Red Sea coastlines enable shipping access though Suez Canal revenues dominate economic thinking. Industrial development lags potential though demographic dividend offers long-term promise. Youth unemployment creates social pressures requiring job-generating investments. Education improvements gradually build skilled workforce supporting advanced manufacturing.
Operating in African markets requires navigating substantial obstacles:
Payment Security: Foreign exchange shortages prevent timely payments even from creditworthy customers. Letter of credit confirmations add security though increasing costs and complexity.
Advance payments protect suppliers though reducing competitiveness. Credit insurance mitigates risks though coverage proves limited for African exposures.
Alternative structures include barter arrangements exchanging equipment for commodities (minerals, agricultural products) though requiring trading expertise. Offshore accounts receive payments in hard currencies avoiding local conversion restrictions. Parent company guarantees leverage multinational strength supporting subsidiary transactions. Escrow arrangements hold funds until delivery verification balancing buyer and seller protections.
Logistics Complexities: Port congestion extends clearance times weeks beyond normal durations. Inland transportation faces poor road conditions, security risks, and bureaucratic checkpoints.
Multiple border crossings for landlocked destinations multiply delays and costs. Temperature extremes damage sensitive components requiring climate-controlled shipping.
Local warehousing buffers supply chain disruptions though tying up capital and risking theft. Inventory management balances availability against obsolescence and deterioration. Reliable freight forwarders prove invaluable navigating complexities though requiring careful selection and performance monitoring. Tracking technologies provide visibility though network coverage gaps create blind spots.
Regulatory Uncertainty: Frequent policy changes alter operating conditions without warning requiring agility. Import duty adjustments affect pricing competitiveness overnight. Local content mandates evolve creating compliance challenges. Tax law modifications impact profitability calculations. Continuous monitoring through local counsel and industry associations provides early warnings though cannot prevent disruptions.
Relationship building with regulators facilitates navigation though crossing into corruption requires ethical boundaries. Transparency International rankings guide risk assessments though individual experiences vary. Compliance programs document due diligence protecting against allegations.
Insurance covers some regulatory risks though exclusions limit protection.
Security Concerns: Equipment theft targets valuable industrial assets requiring physical protection measures. Fenced compounds, security guards, and surveillance systems deter though not eliminate risks. Insurance coverage proves essential though claims processing delays create cash flow pressures. Political violence coverage addresses civil unrest though excluding routine crime.
Kidnapping risks in certain regions affect personnel safety requiring security protocols. Travel advisories restrict movements limiting market coverage. Remote site operations face heightened vulnerabilities requiring comprehensive risk management. Emergency evacuation plans prepare for worst-case scenarios though hopefully never needed.
Despite challenges, African markets offer compelling long-term opportunities for committed players:
Demographic Dividends: Young populations provide labor force growth supporting industrialization if education and job creation keep pace. Urbanization concentrates demand enabling efficient distribution. Middle class expansion increases purchasing power driving manufactured goods consumption and related production investments.
Infrastructure Investments: International development funding (World Bank, AfDB, bilateral aid) supports utility improvements indirectly boosting industrial compressed air demand. Public-private partnerships attract private capital filling government budget gaps. Chinese Belt and Road projects accelerate though facing debt sustainability scrutiny.
Regional Integration: African Continental Free Trade Area (AfCFTA) promises tariff reductions and simplified customs though implementation faces obstacles. Gradual progress creates larger integrated markets achieving economies of scale. Harmonized standards reduce compliance complexity enabling regional distribution strategies.
Technology Leapfrogging: Mobile connectivity enables digital solutions bypassing legacy infrastructure limitations. IoT monitoring proves valuable where maintenance infrastructure sparse enabling remote diagnostics. Solar-powered compressors address electricity gaps though receiver requirements remain similar. Innovative business models (pay-per-use, equipment-as-a-service) overcome capital constraints.
Strategic positioning requires patience accepting longer payback periods balanced against first-mover advantages. Pilot projects validate approaches before scaling commitments. Local
partnerships provide market access though requiring careful structuring protecting interests. Flexible business models adapt to evolving conditions avoiding rigid structures breaking under stress.
Success stories demonstrate viability though requiring sustained efforts beyond quick-win expectations. Organizations viewing Africa as long-term strategic priority rather than opportunistic sidebar achieve meaningful presence building sustainable competitive advantages. Early entrants establish relationships and brand recognition creating barriers for later competitors though only if maintaining consistent commitment through inevitable challenges.
Evaluation criteria weight differently across regions requiring customized strategies:
Criterion | Southeast Asia | Middle East | Africa |
Market Size | Large, growing rapidly | Medium, high value | Small, fragmented |
Growth Rate | 7-9% annually | 5-7% annually | 4-6% annually |
Competition | Intense, price-driven | Moderate, quality-focused | Limited, relationship-based |
Regulatory Complexity | Moderate, improving | High, certification-heavy | Very high, unpredictable |
Payment Risk | Moderate | Low (sovereign) | High |
Infrastructure | Developing well | Excellent | Poor |
Entry Barriers | Moderate | High (local content) | Very high |
Long-term Potential | Very High | High | High (uncertain) |
Southeast Asia: Prioritize Vietnam, Thailand, and Indonesia capturing manufacturing relocation wave. Establish distribution networks with qualified agents supported by regional training centers. Product offerings balance quality and price with tiered options serving diverse segments. Local assembly in Thailand or Malaysia reduces costs while maintaining quality. Digital marketing builds brand awareness complementing field sales efforts.
Investment timeline: 2-3 years for meaningful presence, 5+ years for market leadership. Budget allocation: 60% distribution development, 25% marketing, 15% local operations. Success metrics: market share in target segments, distributor performance, brand recognition surveys.
Middle East: Focus on Saudi Arabia and UAE leveraging transformation initiatives. Pursue joint ventures with established local partners navigating regulatory requirements. Premium positioning emphasizes quality, certification, and lifecycle value over initial price. Service differentiation through rapid response and technical expertise justifies premiums. Government relationship building facilitates large project access.
Investment timeline: 3-5 years for established presence given certification and relationship building needs. Budget allocation: 40% partner development, 30% certification/compliance, 20% marketing, 10% operations. Success metrics: major project wins, certification completions, partner satisfaction. Africa: Selective entry focusing on South Africa, Kenya, and Nigeria as beachheads. Partner with established distributors possessing financial strength and market knowledge. Start with limited product range proving concept before expanding. Flexible payment structures accommodate foreign exchange constraints. Patience required accepting slower growth balanced against first-mover advantages.
Investment timeline: 5-7 years for sustainable presence acknowledging infrastructure and institutional development needs. Budget allocation: 50% partner support, 25% risk mitigation, 15% marketing, 10% operations. Success metrics: payment collection rates, partner stability, repeat orders.
Emerging markets across Southeast Asia, Middle East, and Africa present substantial growth opportunities for air receiver tank manufacturers though requiring nuanced strategies acknowledging regional differences. Southeast Asia's manufacturing boom drives volume growth demanding balanced quality-price offerings supported by robust distribution networks. Middle Eastern
diversification initiatives create high-value opportunities favoring premium positioning and local partnerships navigating complex regulatory landscapes. African markets offer long-term potential though demanding patience and risk management capabilities overcoming substantial obstacles.
Success requires more than exporting existing products applying developed market playbooks.
Adaptation to local conditions including climate specifications, certification requirements, payment structures, and cultural business practices proves essential. Relationship building transcends transactional thinking establishing trust enabling sustainable growth. Long-term commitments demonstrate seriousness distinguishing serious players from opportunistic visitors.
Organizations developing emerging market capabilities gain competitive advantages as mature markets saturate and growth slows. Early movers establish positions creating barriers for later entrants though only if maintaining consistent investment through inevitable challenges. Flexibility adapts to evolving conditions avoiding rigid structures breaking under stress. Learning orientations capture lessons from setbacks improving future performance.
By implementing region-specific strategies outlined in this analysis, manufacturers position effectively capturing emerging market growth while managing risks inherent in dynamic developing economies. The rewards prove substantial for those demonstrating commitment, cultural sensitivity, and operational excellence building lasting competitive advantages in the world's fastest-growing regions.
Specializing in pressure vessel manufacturing, we provide reliable, certified, and customized solutions for customers across diverse industries worldwide.
No.268 Xinda Road, High-tech Industrial Park, Longkou City,Shandong Province
Copyright © 2026 Yantai Xinglong Pressure Vessel Manufacturing Co., Ltd All Rights Reserved.


 عربي
 Español
 Русский
